Quick answer: You can pay off $20,000 in credit card debt with a DIY payoff plan, a 0% balance transfer, a consolidation loan, a debt management plan, or debt settlement. The right path depends on your credit, your income, and how much you can realistically pay each month. All numbers below are illustrative estimates, not quotes or guarantees.
Key takeaways
- At a typical 22% APR, $20,000 costs roughly $365 a month in interest alone if you only pay the minimum.
- Good credit opens up cheaper options like balance transfers and consolidation loans.
- A debt management plan can lower interest without a new loan or a credit score requirement.
- Settlement can cut what you owe but carries real credit, tax and collection risks.
- Comparing two or three paths side by side beats picking the first one you hear about.
Carrying $20,000 on credit cards is stressful, but it is a solvable problem. This guide walks through five realistic ways to tackle it, with example math so you can see how each one might play out for you. If you would rather have someone walk through your numbers, you can request a free, no-pressure debt relief consultation using the form on this page.
What $20,000 in credit card debt really costs
Before choosing a path, it helps to see what the debt costs you today. The math below uses a round 22% APR as an example. Your actual rates may be higher or lower.
- Interest per month: about $20,000 x 22% / 12, or roughly $365.
- Minimum payments only: payoff can take 20+ years and cost well over $20,000 in interest (estimate).
- $600 a month: payoff in roughly 5 years, with total interest near $9,000 (estimate).
- $900 a month: payoff in roughly 2.5 years, with total interest near $4,500 (estimate).
Run your own balances and rates through our debt payoff calculator to see a timeline that fits your budget. For a broader overview, see our credit card debt guide.
Path 1: DIY avalanche payoff
The avalanche method means paying the minimum on every card, then putting every extra dollar toward the card with the highest interest rate. When that card is gone, you roll its payment into the next-highest rate.
Illustrative example: Say you have $20,000 spread across four cards at rates from 17% to 27%, and you pay $800 a month in total. You might finish in about 3 years and pay roughly $6,000 to $7,000 in interest (estimate).
- Best for: people with steady income and the discipline to stick to a plan.
- Pros: no fees, no credit applications, lowest interest of any DIY method.
- Cons: interest stays high, so progress can feel slow without a budget that frees up cash.
If you like quick wins, the snowball method (smallest balance first) costs a bit more in interest but can keep you motivated. Our step-by-step plan to get out of credit card debt covers both approaches, and the budgeting guide can help you find the extra cash.
At 22% APR, $20,000 in balances generates roughly $365 a month in interest before you touch the principal.
Path 2: 0% balance transfer card
A balance transfer moves card balances onto a new card with a 0% introductory APR, often for 12 to 21 months. Transfers usually carry a fee of about 3% to 5% (estimate).
Illustrative example: Transferring $20,000 with a 3% fee adds about $600 up front. If you pay roughly $1,050 a month for 19 months, the balance could reach zero with almost no interest.
- Best for: people with good to excellent credit who can pay off most of the balance during the promo window.
- Pros: potentially the cheapest route when it works.
- Cons: approval for a $20,000 limit is not guaranteed, and any balance left after the promo period gets hit with a regular, often high, APR.
See how this compares to a loan in our consolidation loan vs. balance transfer breakdown.
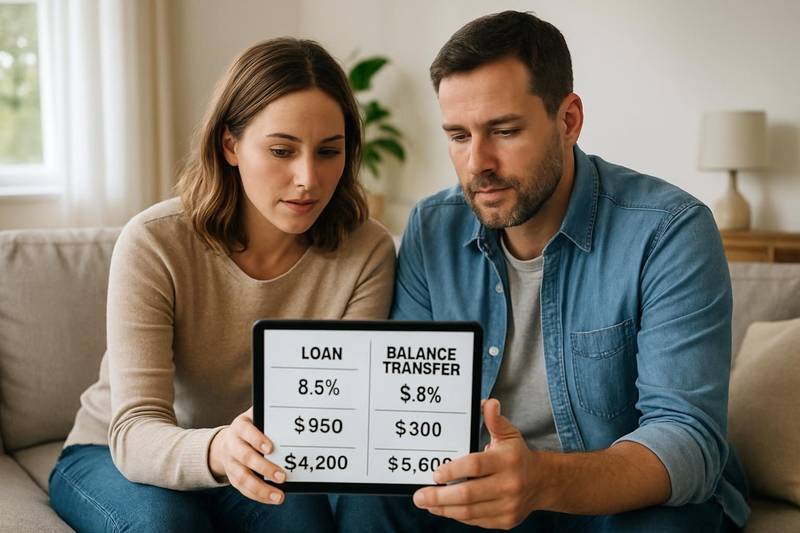
Path 3: Debt consolidation loan
A consolidation loan is a fixed-rate personal loan used to pay off your cards. You then make one predictable monthly payment. Many lenders charge an origination fee of roughly 1% to 8% (estimate).
Illustrative example: A $20,000 loan at 14% APR over 4 years would run about $546 a month and cost roughly $6,200 in interest (estimate). At a 24% rate, the payment jumps to about $653 and interest to about $11,300, so the rate you qualify for matters a lot.
- Best for: people with fair to good credit and stable income who want a fixed end date.
- Pros: one payment, a clear payoff date, often lower than card APRs.
- Cons: origination fees, and the temptation to run the cards back up afterward.
Learn more in our guides to using a personal loan for debt consolidation and debt consolidation in general.
Pro tip: Ask lenders for a soft-pull prequalification first. It shows estimated rates without a hard credit inquiry.
Path 4: Debt management plan (DMP)
A debt management plan is offered through nonprofit credit counseling agencies. The agency negotiates lower interest rates with your card issuers, and you make one monthly payment to the agency, which distributes it to your creditors. Plans typically run 3 to 5 years.
Illustrative example: If your rates drop from about 22% to roughly 8% to 10% (an estimate, since results vary), a $20,000 balance might be paid in about 5 years at around $420 to $450 a month. Agencies commonly charge a small setup fee and a monthly fee, often in the range of $20 to $50 a month (estimate).
- Best for: people who can afford a fixed payment but cannot qualify for a low-rate loan or transfer.
- Pros: lower interest, one payment, no new credit needed.
- Cons: enrolled cards are usually closed, and you must stay on the plan to keep the benefits.
Our explainer on what a debt management plan is and what it costs goes deeper, and credit counseling vs. debt settlement helps you compare it to settlement.
A debt management plan can shrink your interest rate without requiring a new loan or a good credit score.
Path 5: Debt settlement
Debt settlement companies negotiate with creditors to accept less than the full balance. Typically you stop paying cards and deposit money into a dedicated account until there is enough to offer lump-sum settlements.
Illustrative example: If $20,000 were settled for 50% ($10,000) and the company charged a fee of around 15% to 25% of enrolled debt ($3,000 to $5,000, estimate), your total outlay could be $13,000 to $15,000. Settlement is not guaranteed, and some creditors refuse or sue.
- Best for: people in genuine hardship who cannot afford the other options.
- Risks: missed payments can hurt your credit significantly, late fees and interest keep accruing, collection calls or lawsuits are possible, and forgiven debt may be taxable income.
- Fees: under the FTC’s Telemarketing Sales Rule, debt relief companies generally cannot collect fees before they actually settle a debt.
Read whether debt settlement is worth it and how to avoid debt relief scams before signing anything. The FTC also publishes a helpful overview at consumer.ftc.gov.
Side-by-side: which path fits your situation?
- Good credit, can pay $1,000+ a month: balance transfer or consolidation loan.
- Fair credit, can pay $450 to $650 a month: consolidation loan or debt management plan.
- Limited credit options, steady income: debt management plan or DIY avalanche.
- Behind on payments or cash flow is collapsing: compare a hardship program, settlement and other debt relief options, and consider speaking with a nonprofit counselor or bankruptcy attorney.
Also consider calling your issuers about credit card hardship programs, which may temporarily lower interest or payments. If your balance is smaller, see how to pay off $10,000 in credit card debt. Larger balance? Our upcoming guide on paying off $50,000 in credit card debt will help, and you can also read about how to negotiate with credit card companies.
Not sure which path fits? You can request a free debt relief consultation using the form on this page and talk through your numbers with no pressure.
Frequently asked questions
How long does it take to pay off $20,000 in credit card debt?
It depends on your payment and interest rate. At roughly 22% APR, paying $600 a month takes about 5 years, while $900 a month takes about 2.5 years (estimates).
Is it better to use a balance transfer or a consolidation loan?
A balance transfer can cost less if you can pay it off within the promo period and qualify for a high enough limit. A loan gives a fixed payment and payoff date, which suits people who need structure.
Will these options hurt my credit?
Applying for new credit causes a small, temporary dip. A DMP may close your cards, and settlement typically causes more serious damage. Consistent on-time payments help your score over time. See our credit repair and scores guide for more.
Can I settle $20,000 in credit card debt for less?
Sometimes, but there are no guarantees. Creditors decide case by case, fees and taxes can reduce your savings, and your credit will likely be affected. Review the costs in how much debt relief costs first.
This article is for educational purposes only and is not financial, legal or tax advice. Talk with a qualified professional about your situation.
See if you qualify for credit card debt relief
A certified debt specialist will review your options with you, free and with no pressure.